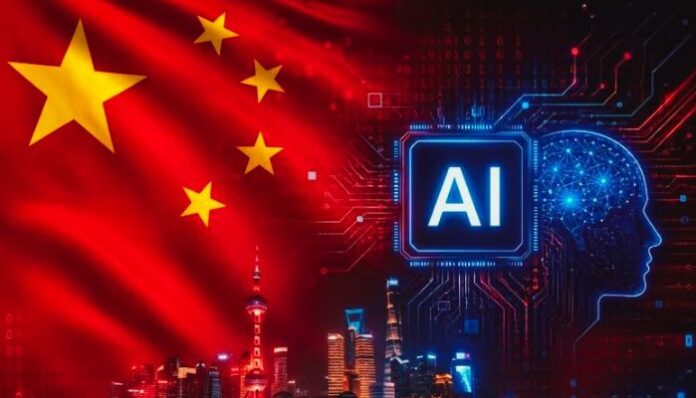
China’s AI and semiconductor stocks have already crashed, even as global technology shares wobble. According to a Reuters report, the retreat has wiped out roughly $480 billion in market value and sent the mainland STAR50 index of tech leaders down about 40% in less than four months, as investors sour on lofty valuations amid worries about AI demand and restrictions on Chinese exports.
The selloff is a worrying sign for fragile world markets and a setback for Beijing’s effort to coax savers into equities to help fund the AI boom. It has also halted a two-year rally and stalled the government’s push for a steadier “slow bull” market rather than the old boom-and-bust cycle. China’s broad blue-chip CSI300 index is down about 20% from its June high.
According to Beijing-based fund manager Dong Baozhen. “The stock market later evolved into a speculative crazy bull, and now we see the bubble bursting.”
The reversal is striking because the Chinese rally had climbed further than markets in the West or elsewhere in Asia. By comparison, U.S. AI stocks have only been nicked, contributing to a 6% pullback in the Nasdaq from a record high set three weeks ago.
Traders said there was no single obvious trigger for the Chinese selloff, though high prices, tax bills and the risk that the U.S. or other governments could ban Chinese equipment from data centres all played a part.
AI-related stocks had grown to 42% of China’s market capitalisation and 57% of turnover across mainland A-shares and Hong Kong H-shares, according to Goldman Sachs. In a market dominated by small investors, few have been able to avoid the pain.
Retail favourites slide
Robot-maker Unitree, which was 8,000 times oversubscribed by retail buyers at its listing, has halved since it began trading in August. Chipmaker CXMT has lost more than a quarter of its value in the past month.
Chipmakers MetaX Integrated Circuits and Moore Threads Technology, which jumped 700% and 400% respectively on their market debuts last year, have also halved in value since July.
Chen Wensheng, a small business owner and investor from southern Hainan province, said he joined the rally because he believed official support was behind companies such as Unitree, which counted state-backed funds among its investors. Chen and his friends are now nursing losses.
Frustration that a Beijing-backed investment theme has ended so badly has pushed many investors into defensive assets and is likely to slow equity fundraising by technology companies.
Shares in optical components makers Zhongji Innolight and Eoptolink Technology are down roughly 60% from their June and July highs, partly because Washington is moving towards banning the one-time market darlings from supplying U.S. data centres.
The STAR50 index still trades at around 100 times trailing earnings, down from a high of nearly 250 but far above the Nasdaq 100’s multiple of about 30. Investors worry the selloff could worsen before it improves.
“What’s happening is now going to put a stop to many of the companies trying to get themselves listed,” said Hong Hao, managing partner and chief investment officer at Lotus Asset Management in Hong Kong.
‘All bubbles inevitably burst’
The frenzy and its aftermath contrast with authorities’ efforts to improve returns and reduce volatility by cracking down on leverage and high-frequency trading. State-backed investors sold into rallies to keep gains in check.
China’s market regulator, the China Securities Regulatory Commission, did not immediately reply to questions faxed by Reuters last week.
CSRC Chairman Wu Qing met market participants earlier this month to hear suggestions on improving capital markets, the regulator said on its website. Some in the investment community say the boom has damaged the market’s structure.
“Overemphasising the ‘technology content’—that is, the weighting of tech companies by market value in major indexes—leads to a deviation, even a distortion, in capital behaviour,” said Leo Wang, partner at Beijing-based Qianchuang Capital. “This created a severe bubble in certain sectors and a serious drain on others.”
Some investors see value in the selloff. They argue it is neither surprising nor harmful to long-term market reforms that have helped improve returns, particularly income, in recent years.
Asia funds in general remain overweight on China, according to HSBC research, even though they have been sellers over the past three months.
Goldman Sachs has Innolight and CXMT among dozens of Chinese AI stocks on a revamped recommendation list published earlier this month. BNP Paribas Securities strategist William Bratton has said the market offers buying opportunities for careful investors.
Still, many mainland investors are looking at other sectors or waiting for even lower valuations before buying.
“Just like all other Chinese manufacturers, (chipmakers and AI suppliers) will eventually end up in a price war,” said fund manager Wang Zhuo, partner at Shanghai Zhuozhu Investment Management.
“There’s no exception,” he said. “All bubbles inevitably burst.”